[E-11] CREATE MORE: WHY RA 12066 REWROTE PARTS OF THE CREATE FRAMEWORK
Tax Code Evolution Series No. 11
CREATE was supposed to reform corporate taxation and tax incentives. CREATE MORE came soon after and changed important parts of that framework—including incentives, VAT treatment, local sales, compliance, and the administration of registered business enterprises.
If TRAIN changed major tax rates and CREATE reshaped corporate taxation and incentives, what happened next?
Congress revisited the CREATE framework.
The result was Republic Act No. 12066, officially titled the Corporate Recovery and Tax Incentives for Enterprises to Maximize Opportunities for Reinvigorating the Economy Act, commonly called CREATE MORE.
Approved on November 8, 2024, RA 12066 further amended numerous provisions of the 1997 NIRC, including Sections 27, 28, 32, 34, 57, 106, 108, 109, 112, 135, 237-A, 269, 292–301 and 308–311, and inserted new Sections 135-A, 295-A, 296-A and 297-A.
The important point is this:
CREATE MORE did not replace CREATE with a completely separate tax system. It further amended the NIRC’s existing CREATE framework.
And that makes CREATE MORE another important chapter in understanding the living Philippine Tax Code.
Where does CREATE MORE fit?
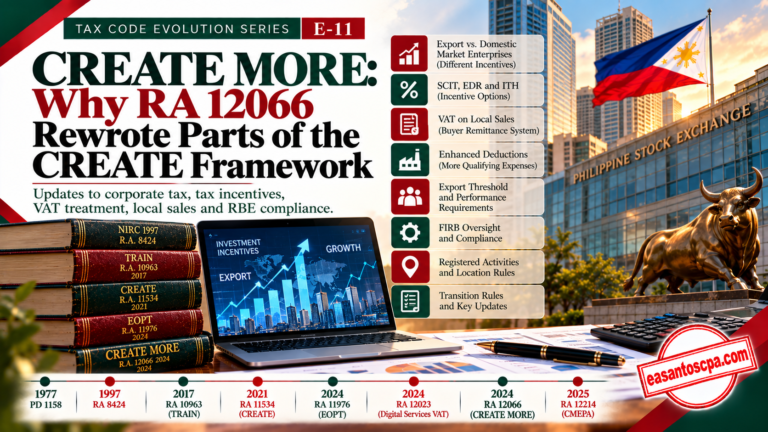
Our Tax Code Evolution now looks like this:
PD 1158 — 1977 NIRC
↓
RA 8424 — 1997 NIRC
↓
RA 10963 — TRAIN
↓
RA 11534 — CREATE
↓
RA 11976 — EOPT
↓
RA 12023 — Digital Services VAT
↓
RA 12066 — CREATE MORE
↓
RA 12214 — CMEPA
↓
Current NIRC, as amended
This sequence is important because it prevents a common research mistake:
Treating CREATE as if it were still the complete and current incentive framework.
It is not.
CREATE MORE further amended CREATE.
Why did CREATE MORE become necessary?
CREATE introduced a new framework for:
- corporate income taxation;
- registered business enterprises;
- income tax holidays;
- special corporate income tax;
- enhanced deductions;
- VAT and customs incentives;
- the Strategic Investment Priority Plan;
- the Fiscal Incentives Review Board; and
- performance-based incentives.
But after CREATE’s implementation, businesses and government agencies encountered practical questions involving:
- the treatment of local sales by registered business enterprises;
- VAT on purchases and sales;
- incentive periods;
- transition rules;
- export thresholds;
- the treatment of domestic-market enterprises;
- enhanced deductions;
- administration of incentives;
- processing of applications; and
- coordination between the BIR and investment promotion agencies.
CREATE MORE therefore modified significant portions of the CREATE architecture.
The law itself states that it further amends the NIRC of 1997, as amended.
CREATE MORE kept the regular corporate tax rate at 25%
One important point needs clarification.
CREATE MORE did not generally reduce the ordinary corporate income-tax rate below the 25% rate established by CREATE.
Under amended Section 27, the regular corporate income-tax rate remains 25%.
However, qualifying corporations with:
- net taxable income not exceeding ₱5 million, and
- total assets not exceeding ₱100 million, excluding the land on which the business’s office, plant and equipment are situated,
remain subject to the 20% rate under the statutory conditions.
CREATE MORE also expressly provides a 20% rate for the taxable income derived by an RBE from registered projects or activities under the Enhanced Deductions Regime.
That distinction is important:
20% under the ordinary small-corporation rule is not the same thing as 20% under the RBE Enhanced Deductions Regime.
The legal basis and conditions are different.
CREATE MORE strengthened the distinction between export and domestic-market enterprises
One of the most important features of the amended incentive system is the distinction between:
Registered Export Enterprises
and
Registered Domestic Market Enterprises
The available incentive combinations differ.
Under amended Section 295:
Registered Export Enterprises may choose:
ITH → SCIT or EDR
or
SCIT immediately
or
EDR immediately
subject to the statutory conditions and period of availment.
Registered Domestic Market Enterprises may choose:
ITH → EDR
or
EDR immediately.
The selected incentive package is generally irrevocable for the applicable incentive period.
This is a significant change in how businesses must think about incentives.
The question is no longer simply:
“Are we registered with an investment promotion agency?”
The more important question is:
“What kind of registered enterprise are we, and which incentive package does the law allow us to choose?”
The 5% SCIT remains—but primarily for export enterprises
CREATE MORE retains the Special Corporate Income Tax (SCIT).
For qualified export enterprises, the SCIT is generally:
5% of gross income earned
in lieu of national and local taxes and local fees and charges, subject to the statutory framework.
This is important because the phrase:
“5% tax”
is often used loosely.
It should not be understood as:
“Every PEZA/economic-zone company pays only 5%.”
The taxpayer must determine:
- whether it is an export enterprise;
- whether it elected SCIT;
- whether the project is registered;
- whether the incentive period is still running;
- whether the conditions remain satisfied; and
- whether the income being reported belongs to the registered project or activity.
The law itself distinguishes registered-project income from income derived from non-registered activities.
CREATE MORE expanded the Enhanced Deductions Regime
The Enhanced Deductions Regime (EDR) is another major part of the CREATE MORE framework.
EDR is available to both:
- export enterprises; and
- domestic market enterprises,
subject to the applicable conditions.
CREATE MORE expanded the types of deductions that may be available.
Among the notable additional deductions are:
- 100% additional deduction on power expense incurred in the taxable year;
- a reinvestment allowance for qualifying manufacturing and tourism industries;
- 50% additional deduction for expenses relating to exhibitions, trade missions or trade fairs; and
- an enhanced Net Operating Loss Carry-Over (NOLCO) mechanism for qualified losses arising during the first three years from commercial operations.
This means that EDR is not simply:
“a lower corporate tax rate.”
It is a taxable-income reduction mechanism.
The actual tax benefit therefore depends on the taxpayer’s qualifying expenses, income and compliance with the conditions of the regime.
CREATE MORE made EDR more strategically important
Consider two corporations.
Corporation A
Uses a special 5% SCIT regime.
Corporation B
Uses the EDR.
Their tax computations can look fundamentally different.
Under SCIT, the calculation centers on gross income earned.
Under EDR, the calculation involves taxable income after allowable deductions, including qualifying enhanced deductions.
Therefore, the question:
“Which incentive is better?”
cannot be answered merely by comparing:
5% vs. 20%.
The business needs to consider:
- gross income;
- taxable income;
- qualifying expenses;
- power costs;
- labor;
- research and development;
- training;
- reinvestment;
- NOLCO;
- export profile;
- local sales;
- incentive duration; and
- compliance costs.
That is why incentive selection is fundamentally a tax-planning and compliance decision, not merely a rate comparison.
CREATE MORE also changed VAT treatment of local sales
This is one of the most significant practical changes.
Under amended Section 295(D):
Local sales by an RBE are generally subject to 12% VAT, regardless of the RBE’s income-tax incentive regime and regardless of where the transaction occurs, unless the sale is otherwise exempt or zero-rated under the NIRC.
This means that the old mental shortcut:
“The seller is inside an economic zone, so the sale is automatically VAT-free.”
is no longer an adequate way to analyze the transaction.
CREATE MORE looks at the nature of the sale and the statutory VAT rules, not simply the physical location of the RBE.
What is a “local sale” under CREATE MORE?
The amended framework treats local sales as sales of goods or services to:
- domestic market enterprises; or
- non-RBEs,
regardless of whether the transaction takes place within a freeport or economic zone.
That is a major conceptual shift.
Imagine an RBE operating inside an economic zone.
It sells goods to a Philippine domestic customer.
The fact that:
- the seller is inside the zone,
- the customer is outside the zone,
does not automatically make the transaction VAT-free.
The transaction must be tested under the local-sales rules of the amended NIRC.
CREATE MORE also shifted the VAT payment mechanism
This is perhaps one of the most unusual features.
For covered local sales, the law provides that:
the buyer bears the liability to pay and remit the VAT to the government.
This was implemented by RR No. 9-2025.
For covered B2B local sales, the RBE seller bills the transaction inclusive of VAT and separately identifies the VAT on local sales, while the buyer pays the corresponding VAT to the BIR rather than paying that VAT amount to the RBE seller. This is a major compliance change.
It means that a transaction can involve:
RBE seller → invoice
but
buyer → VAT remittance to BIR
rather than the traditional:
buyer → seller → BIR
But the BIR later had to refine the rules
The implementation of the local-sales VAT system did not stop with RR No. 9-2025.
The BIR subsequently issued RR No. 1-2026, amending RR No. 9-2025.
Among other things, RR No. 1-2026:
- clarified filing and payment rules;
- introduced optional VAT registration for certain SCIT/GIE RBEs;
- extended the system-reconfiguration deadline; and
- excluded certain enterprises and transactions from the buyer-remittance mechanism.
This is another textbook example of Tax Code Evolution:
The statute establishes the rule.
The regulation operationalizes it.
A later regulation may refine how the rule works.
Not every RBE local sale falls under the buyer-remittance mechanism
RR No. 1-2026 expressly excludes certain transactions from the Section 295(D) buyer-payment mechanism.
These include certain:
- VAT zero-rated goods;
- VAT zero-rated services;
- VAT-exempt transactions; and
- transactions otherwise exempt or zero-rated under Title XIII.
It also addresses VAT-registered domestic-market enterprises that do not qualify for certain Title XIII VAT benefits.
For those enterprises, the regulation recognizes that imposing the buyer-remittance mechanism could create accumulated input VAT concerns and therefore provides a different treatment.
So once again:
“RBE local sale = buyer pays VAT” is an oversimplification.
The actual transaction must be classified first.
The 70% export threshold became very important
CREATE MORE also ties several incentives to an export threshold.
For certain export-oriented enterprises, the law requires that export sales be at least:
70% of total annual production or output of the preceding taxable year.
The amended NIRC uses this threshold in determining continued eligibility for certain VAT and duty incentives.
If the enterprise fails to meet the threshold, it can lose eligibility for certain benefits in the immediately succeeding year.
This means that export status is not merely a label in a registration certificate.
It can become an annual compliance metric.
Why is that significant?
Imagine an RBE whose business has historically been export-oriented.
But in one year:
- export sales decline;
- domestic sales increase;
- total production remains substantial.
The business may still think:
“We’re an export enterprise.”
But the statutory test may require a more precise analysis.
The taxpayer must examine:
- total annual production/output;
- export sales;
- the preceding taxable year;
- the applicable incentive;
- the applicable statutory threshold; and
- the consequences of failing the threshold.
Thus:
Incentive eligibility can depend on actual business performance—not merely on the taxpayer’s historical registration status.
CREATE MORE extended VAT and duty benefits in certain cases
For qualifying RBEs, VAT exemption on importation and VAT zero-rating on local purchases can continue for the registration period, subject to statutory conditions.
For registered export enterprises, continued access to these benefits is tied, among other things, to:
- continued compliance with registration conditions; and
- the applicable export threshold.
This is significant because the duration of an incentive is no longer necessarily identical across all components.
A business may need to separately analyze:
Income-tax incentives
VAT incentives
Customs-duty incentives
Local tax treatment
Each may have its own statutory conditions and duration.
CREATE MORE also introduced an RBE local tax
Under amended Section 294(F), the concerned local government unit may impose an RBE local tax of not more than 2% of gross income during the ITH and EDR periods, subject to the statutory framework.
That local tax is intended to be in lieu of local taxes, fees and charges imposed by the LGU under the Local Government Code.
However:
The RBE local tax does not apply to RBEs under SCIT.
This is another reason why taxpayers should not look only at the national income-tax rate.
The incentive regime can have implications for:
- national taxes;
- local taxes;
- VAT;
- customs duties;
- fees; and
- other charges.
CREATE MORE created an RBE Taxpayer Service within the BIR
One of the less-publicized but important reforms is new Section 295-A.
It creates a separate service within the BIR to support the end-to-end tax compliance of registered business enterprises.
The law directs the Commissioner to prescribe:
- the manner of filing returns;
- the place of filing;
- payment procedures; and
- simplified filing and payment processes for RBEs.
This is significant because RBEs often operate under a tax system involving multiple government institutions:
- BIR;
- BOC;
- BOI;
- PEZA;
- other investment promotion agencies;
- LGUs.
CREATE MORE recognizes the need for a more specialized tax-administration interface.
CREATE MORE changed the processing of incentive applications
New Section 297-A provides a statutory processing period for tax-incentive applications.
The FIRB and investment promotion agencies are generally required to issue a decision within:
20 working days
from receipt of all required documents.
An extension may be allowed only once and cannot exceed an additional:
20 working days.
This ties the incentive system to the broader government policy of ease of doing business under RA 11032.
So CREATE MORE was not only about tax rates.
It also attempted to improve the administrative process of obtaining incentives.
The Strategic Investment Priority Plan became even more important
CREATE MORE further strengthened the role of the Strategic Investment Priority Plan (SIPP).
The SIPP identifies projects and activities that the government considers strategically important.
CREATE MORE provides that:
Investment Promotion Agencies should not accept applications unless the project or activity is listed in the SIPP.
The SIPP is intended to consider factors such as:
- the Philippine Development Plan;
- high-skilled jobs;
- domestic supply chains;
- sophistication of products and services;
- import substitution;
- foreign investment;
- regional development; and
- strategic economic priorities.
The SIPP is also subject to review and amendment every three years, unless a supervening event requires earlier review.
This is a crucial point for prospective investors:
Being a profitable business does not automatically make a project incentive-eligible.
The project must fit within the government’s current investment priorities.
Incentives are now increasingly performance-based
CREATE already emphasized:
- performance;
- targeting;
- time limitations; and
- transparency.
CREATE MORE strengthens that philosophy.
The FIRB has expanded functions involving:
- performance metrics;
- monitoring;
- evaluation;
- cost-benefit analysis;
- verification of RBE compliance;
- oversight of investment promotion agencies; and
- possible cancellation, suspension or withdrawal of incentives for material violations.
This means:
An incentive is not simply a tax privilege granted once and forgotten.
It is increasingly treated as a conditional fiscal investment by the government.
The FIRB can cancel, suspend or withdraw incentives
CREATE MORE gives the FIRB substantial oversight authority.
For flagrant and material violations of conditions imposed in the grant of incentives, the FIRB can take action involving:
- cancellation;
- suspension;
- withdrawal; and
- referral for assessment and collection of taxes and duties that may become due.
The law also provides due-process mechanisms.
This is important for taxpayers because it changes the mindset from:
“We already received the incentive.”
to:
“We must continue satisfying the conditions of the incentive.”
Noncompliance with reportorial requirements can have serious consequences
CREATE MORE amended Section 308.
For failure to comply with certain filing/reportorial requirements with the appropriate investment promotion agency or failure to show proof of required BIR electronic filing, the statutory penalties include:
First violation
₱100,000 fine
Second violation
₱500,000 fine
Third violation
Cancellation of RBE registration
subject to the statutory rules.
This is a significant warning for businesses operating under incentives.
The tax benefit may be substantial.
But the compliance burden is also substantial.
Incentive compliance is therefore broader than tax returns
An RBE may have to maintain compliance with:
- BIR tax returns;
- BIR payments;
- books and records;
- invoices;
- IPA reportorial requirements;
- performance commitments;
- export ratios;
- employment commitments;
- registered activities;
- location restrictions;
- importation conditions;
- VAT documentation;
- customs requirements.
This is why:
RBE compliance is not simply “BIR compliance.”
It is an integrated compliance environment.
CREATE MORE also changed the rules on where registered activities may be conducted
Under amended Section 309, a qualified registered project or activity under an IPA administering an economic zone or freeport generally must be conducted within the geographical boundaries of the relevant zone or freeport.
Activities conducted outside those boundaries generally do not qualify for the incentives.
However, CREATE MORE recognizes telecommuting/work-from-home arrangements, subject to the applicable rules, with a statutory limit of not more than 50% of the total workforce under the provision.
This is particularly relevant after the pandemic.
The tax incentive framework had to recognize a modern business reality:
Employees do not necessarily work physically inside the registered facility every day.
But flexibility does not mean unlimited freedom to move the registered activity outside the approved location.
CREATE MORE also contains important transition rules
This is one of the most difficult areas for existing RBEs.
A business may have:
- been registered before CREATE;
- transitioned into CREATE;
- obtained a 5% gross-income regime;
- received an ITH;
- obtained VAT and customs incentives; and
- continued operating after CREATE MORE.
CREATE MORE therefore contains specific rules for enterprises with incentives granted before CREATE.
For example, certain RBEs previously enjoying the 5% gross-income incentive are allowed to continue that regime under specified transition rules, while other pre-CREATE incentives are subject to statutory deadlines and transition provisions.
This is why the question:
“What does CREATE MORE say?”
is not always enough.
An existing RBE may need to ask:
“When was my project registered, what incentive was granted, and what transitory provision applies to me?”
CREATE MORE is also a lesson in grandfathering
Tax incentives often create long-term expectations.
A business may make an investment based on the law existing at the time of registration.
When Congress changes the law, a difficult question arises:
Does the new law immediately change the taxpayer’s existing incentive?
CREATE MORE therefore contains transition rules rather than simply wiping out every previous incentive arrangement.
This is a classic issue in tax-law evolution:
New law
versus
existing vested or contractual/statutory incentive arrangements
The answer must come from the applicable statute, certificate, implementing rules and transition provisions.
CREATE MORE and tax-exemption jurisprudence
The Supreme Court has long held that tax exemptions and tax privileges must be based on clear statutory authority.
This principle remains important under CREATE MORE.
A business cannot simply argue:
“We’re an RBE, therefore every purchase is VAT zero-rated.”
The taxpayer must establish:
- the legal basis for the incentive;
- the registered project/activity;
- the taxpayer’s classification;
- the applicable incentive regime;
- the relevant period;
- the transaction’s connection to the registered activity; and
- compliance with documentary requirements.
The Supreme Court has repeatedly applied strict-construction principles to tax exemptions and privileges.
The CREATE MORE framework reinforces this approach by repeatedly tying incentives to registered projects or activities and statutory conditions.
CREATE MORE also shows why BIR issuances matter
Consider the evolution of VAT on RBE local sales:
RA 12066
creates the statutory rule.
↓
RR No. 9-2025
implements the local-sales VAT mechanism.
↓
RMC No. 67-2025
circularizes related implementation guidance.
↓
RR No. 10-2025
clarifies VAT zero-rating on qualifying local purchases.
↓
RMC No. 66-2025
clarifies documentary requirements.
↓
RR No. 1-2026
further amends the local-sales rules and provides optional VAT registration and exclusions.
This is precisely why tax research must follow:
Mother law → amendment → regulation → subsequent amendment → clarification → current rule.
The 2026 rules show that CREATE MORE is still evolving
As of October 8, 2026, the CREATE MORE framework continues to generate implementation issuances.
For example, the BIR’s 2026 issuances include RR No. 1-2026, specifically addressing VAT on local sales of RBEs under Section 295(D).
More recently, RMC No. 105-2026, dated September 29, 2026, circularized DOF Order No. 026-2026, concerning the terms and conditions for the grant of the Enhanced Deduction Regime under Section 294(C) of the NIRC, as amended by RA 12066.
That is extremely relevant.
It means that as of October 2026, the EDR framework is not merely a 2024 statutory concept.
It continues to receive detailed administrative implementation.
A simple real-life example
Suppose a corporation is an RBE operating inside an economic zone.
It sells:
- 80% of its output to foreign customers; and
- 20% to Philippine domestic customers.
The corporation might assume:
“We’re an export enterprise, so all our sales are under our incentive regime.”
That is too broad.
The taxpayer may need to separately analyze:
Foreign sales
Potential export treatment.
Domestic sales
Potential local-sales VAT.
Registered project
Whether each sale belongs to the approved registered activity.
Export threshold
Whether the enterprise maintains the statutory export percentage.
VAT incentives
Whether purchases remain directly attributable to the registered activity.
Income-tax incentive
Whether the enterprise elected ITH, SCIT or EDR.
Reportorial compliance
Whether all BIR and IPA requirements were satisfied.
The same corporation can therefore have different tax consequences for different streams of transactions.
Another example: SCIT vs EDR
Imagine two qualified export enterprises with similar operations.
Company A
Chooses 5% SCIT.
Company B
Chooses EDR.
Company A’s tax computation centers on gross income earned.
Company B’s computation centers on taxable income and qualifying enhanced deductions.
If Company B has significant qualifying:
- power expenses;
- research and development;
- training;
- labor;
- reinvestment;
- trade-promotion expenses;
its EDR computation may produce a very different result from Company A’s SCIT calculation.
Therefore:
There is no universal “best” CREATE MORE incentive package.
The appropriate regime depends on the business model and statutory eligibility.
CREATE MORE also changed the role of the SIPP
This is strategically important.
The incentive system is no longer simply:
“Choose a location and get tax incentives.”
The government is attempting to use incentives to direct capital toward activities considered strategically important.
The SIPP can identify:
- priority industries;
- strategic projects;
- location priorities;
- industry tiers;
- sophisticated activities;
- research and development;
- artificial intelligence;
- cybersecurity;
- data centers;
- high-value manufacturing; and
- other activities considered important for structural transformation.
That means:
Tax incentives are increasingly becoming an industrial-policy tool.
CREATE MORE recognizes high-value domestic market enterprises
CREATE MORE also recognizes a category of:
High-Value Domestic Market Enterprise (HVDME).
The law defines this category based on significant investment capital and/or export-related thresholds.
This is important because the incentive framework is no longer designed exclusively around companies whose primary business model is export.
The law can also recognize strategically important domestic-market investments.
This reflects a broader policy objective:
The Philippines can use tax incentives not only to attract exporters, but also to build strategic domestic capacity.
What CREATE MORE teaches us about Philippine tax law
By now, the pattern is unmistakable.
TRAIN
Changed major tax rates and bases.
CREATE
Restructured corporate taxation and incentives.
EOPT
Changed the mechanics of taxpayer compliance.
Digital Services VAT
Expanded VAT into the digital economy.
CREATE MORE
Reworked important parts of the corporate-tax and incentive framework again.
This is why the phrase:
“under CREATE”
may be legally incomplete.
The better phrase is:
“under the NIRC as amended by CREATE, CREATE MORE and subsequent applicable laws and implementing issuances.”
LEGAL BASIS
Constitutional foundation
CREATE MORE operates within the constitutional framework governing taxation and investment policy, including:
- Article VI, Section 28(1) — uniform and equitable taxation and the progressive-taxation mandate;
- Article III, Section 1 — due process and equal protection;
- Article XII, Section 10 — Congress may provide incentives to encourage investments and the transfer of technology, subject to constitutional requirements.
The incentive framework must therefore remain grounded in statute and constitutional limits.
Principal statute
Republic Act No. 12066
Approved: November 8, 2024
CREATE MORE amended numerous provisions of the NIRC of 1997, as amended, and introduced new provisions governing:
- corporate income taxation;
- VAT;
- registered business enterprises;
- incentives;
- EDR;
- SCIT;
- ITH;
- FIRB oversight;
- SIPP;
- RBE compliance;
- VAT on local sales;
- transition rules; and
- electronic reporting.
The Act became effective 15 days after publication in the Official Gazette or a newspaper of general circulation.
Important implementing issuances
RMC No. 42-2025
Circularized the Implementing Rules and Regulations of Title XIII of the NIRC, as amended by RA 12066.
RR No. 9-2025
Implemented the treatment of local sales by RBEs, including the buyer’s liability to pay and remit VAT for covered B2B transactions.
RR No. 10-2025
Further addressed VAT zero-rating on qualifying local purchases by RBEs.
RMC No. 66-2025
Clarified documentary requirements for VAT zero-rating on local purchases and recognized the IPA-issued VAT Zero-Rate Certificate as the primary documentary basis under the clarified framework.
RR No. 1-2026
Further amended RR No. 9-2025, including:
- optional VAT registration for certain SCIT/GIE RBEs;
- filing/payment rules;
- exclusions from the buyer-remittance mechanism; and
- related transition/system matters.
RMC No. 105-2026 / DOF Order No. 026-2026
As of September 29, 2026, the BIR had also circularized DOF Order No. 026-2026 prescribing terms and conditions for the grant of the Enhanced Deduction Regime under amended Section 294(C).
Jurisprudence: what should we watch?
As of October 8, 2026, the CREATE MORE framework is still relatively new compared with the long body of jurisprudence interpreting earlier NIRC provisions.
Therefore, it is important not to manufacture a “CREATE MORE Supreme Court doctrine” where none yet exists.
Instead, the existing jurisprudence remains relevant for underlying principles, particularly:
Tax exemptions are strictly construed
Tax exemptions and preferential tax treatment must be grounded on clear statutory authority.
Tax statutes are interpreted according to their text and purpose
But administrative issuances cannot override the statute they are supposed to implement.
Taxpayer rights and due process remain relevant
Cancellation, withdrawal or denial of incentives must operate within the procedural safeguards provided by law.
Administrative rules must remain within delegated authority
The implementing regulation may explain how the statute works, but it cannot create a tax or exemption that Congress did not authorize.
These established principles are particularly important as the CREATE MORE framework continues to generate implementing rules.
The taxpayer lesson: an incentive is a compliance relationship
For an ordinary taxpayer, the relationship with the BIR may be summarized as:
Register → transact → record → file → pay.
For an RBE, the relationship can be more complex:
Register project/activity
↓
Obtain incentive approval
↓
Select applicable incentive package
↓
Conduct only qualified registered activities
↓
Maintain performance commitments
↓
Maintain export/investment thresholds where applicable
↓
Maintain VAT/customs documentation
↓
File BIR returns
↓
Submit IPA/FIRB reports
↓
Maintain books and records
↓
Pass compliance monitoring
That is why:
Tax incentives create compliance obligations as well as tax benefits.
What should taxpayers remember?
If you remember only eight things about CREATE MORE:
1. CREATE MORE amended CREATE.
It did not create a completely separate tax code.
2. The ordinary corporate income-tax rate remains 25%.
Certain qualifying corporations and RBEs under EDR may be subject to the statutory 20% rate.
3. Export and domestic-market enterprises do not have identical incentive choices.
Their available packages differ.
4. The 5% SCIT is not a universal “economic-zone tax.”
It is a statutory incentive for qualified export enterprises subject to the applicable conditions.
5. Local sales by RBEs received a major VAT change.
Covered local sales are generally subject to 12% VAT, and the buyer may bear the remittance obligation under the statutory framework.
6. Incentives increasingly depend on performance.
Export ratios, registered activities, employment and other metrics can affect entitlement.
7. Incentive compliance is not just BIR compliance.
IPA, FIRB, BOC and other government requirements may also matter.
8. CREATE MORE itself is still evolving through implementation.
The 2026 BIR rules demonstrate that the operational framework continues to develop.
The Tax Code Evolution Lesson
We can now see why Philippine tax law cannot be studied by memorizing tax laws one by one.
CREATE established a new corporate-tax and incentive architecture.
CREATE MORE then modified that architecture.
RRs and RMCs translated the amendments into operational rules.
2026 issuances continue refining those rules.
So the proper research chain becomes:
CREATE → CREATE MORE → implementing regulations → subsequent amendments → current BIR issuances → actual taxpayer facts
And that leads to one of the most important principles in this entire series:
A taxpayer’s “incentive” is not a single tax rate. It is a legal package with conditions, periods, documentation, performance requirements and continuing compliance obligations.
Related Philippine Tax Code Evolution Articles
[E-01] Before the NIRC: Where Did Philippine Tax Law Begin?
[E-02] From Act No. 1189 to Act No. 2339: How Philippine Internal Revenue Law Started To Evolve
[E-03] The Commonwealth Tax Code: How CA 466 Became the National Internal Revenue Code
[E-04] From CA 466 To PD 1158: Why the 1977 NIRC Was Another Recodification
[E-05] From The 1980s-1990s Tax Reforms To RA 8424: How the Modern NIRC Emerged
[E-06] The 1997 NIRC: How the Modern Philippine Tax Code Is Structured
[E-07] Train: Why RA 10963 Changed The 1997 NIRC
[E-08] Create: How RA 11534 Reshaped Corporate Taxation And Tax Incentives
[E-09] EOPT: Why RA 11976 Changed How Taxpayers Comply
[E-10] Digital Services VAT: How RA 12023 Brought Digital Services Into The Philippine Vat System
[E-11] Create More: Why RA 12066 Rewrote Parts Of The Create Framework
[E-12] CMEPA: How Ra 12214 Changed The Taxation Of Capital Markets And Financial Transactions
[E-13] The Current NIRC: How To Read The National Internal Revenue Code As Amended In 2026
[E-14] How A Philippine Tax Rule Is Born: From Legislation To Implementation
[E-15] How To Research Philippine Tax Law: Finding The Original Rule, Its Amendments, And The Current Legal Basis
Next:
[E-12]
CMEPA: HOW RA 12214 CHANGED TAXATION OF CAPITAL MARKETS AND FINANCIAL TRANSACTIONS
After corporate taxation, tax incentives, invoicing and digital services, another major piece of the NIRC evolved:
the taxation of investments, capital markets and financial transactions.
The next article will trace how RA 12214 — the Capital Markets Efficiency Promotion Act (CMEPA) changed the tax treatment of:
- stock transactions;
- dividends;
- interest;
- securities;
- investment products;
- financial intermediaries; and
- capital-market transactions.
And once again, the key question will be:
What did the law change—and what is the rule today after subsequent amendments and implementing issuances?
Taxpayer Literacy is a Must!
Editorial Note
Current as of October 31, 2026.
This article is part of the Tax Code Evolution Series of easantoscpa.com Articles & Insights.
The purpose of this series is to help taxpayers understand where Philippine tax rules came from, how they evolved, and why today’s tax rules must be read together with their amendments, implementing issuances and jurisprudence.
Taxpayer Literacy is a Must!
Need Help With a Tax or Compliance Concern?
Understanding your obligations is the first step. Building the right compliance system is the next.
If your business needs professional guidance regarding BIR compliance, bookkeeping, documentation, tax concerns, or compliance review, you may discuss your specific circumstances with us.
BOOK A CONSULTATION →
Disclaimer
This article is provided for educational and conceptual purposes only and does not constitute tax, legal, accounting, or other professional advice. Tax rules and administrative requirements may change, and their application depends on the taxpayer’s particular facts and circumstances. Consult a qualified professional regarding your specific situation.
LEARN • STRENGTHEN • COMPLY
Trainings, Seminars & Webinars
Practical learning for business owners, professionals and teams.
- services@easantoscpa.com
- +63 916 587 1528
- Topaz Building, Kamias Road, Quezon City
- Office visit: By Appointment only.
- Strictly NO Walk-In
- Affiliate: ptabcpsolutions.com
Disclaimer: Posts are provided for educational and conceptual purposes only. They do not constitute professional advice. You are advised to consult a qualified professional regarding your specific circumstances.