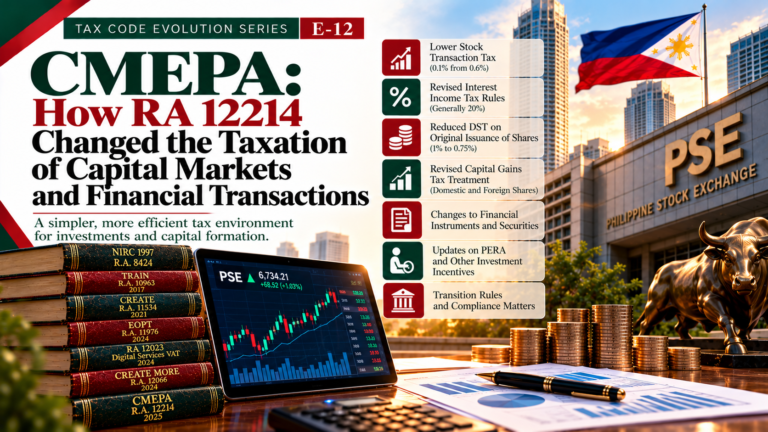
[E-12] CMEPA: HOW RA 12214 CHANGED THE TAXATION OF CAPITAL MARKETS AND FINANCIAL TRANSACTIONS
Tax Code Evolution Series No. 12
Capital Markets Efficiency Promotion Act (CMEPA)
Last reviewed: October 30, 2026
Part I — Tax Code Evolution | easantoscpa.com
A tax reform that goes beyond ordinary business taxation
When Philippine taxpayers hear about tax reform, they often think of income tax, VAT, withholding tax, or the filing of tax returns.
But some taxes arise from something different: how money is invested, how securities are traded, how financial instruments are issued, and how investment income is earned.
Consider these situations:
An individual earns interest from a bank deposit.
An investor receives dividends from shares.
A shareholder sells shares through the stock exchange.
A corporation transfers shares that are not traded on an exchange.
A business issues a debt instrument to raise capital.
These transactions do not necessarily receive the same tax treatment. Their consequences depend on the nature of the income, the instrument, the parties, and the transaction.
This is the setting in which Republic Act No. 12214, or the Capital Markets Efficiency Promotion Act (CMEPA), becomes important.
CMEPA is another chapter in the continuing evolution of the National Internal Revenue Code (NIRC). Like TRAIN, CREATE, EOPT, and CREATE MORE, it changes particular provisions of the existing Code rather than creating an entirely separate tax code.
Its broader purpose is to improve the tax environment for capital formation and investment by simplifying and adjusting selected taxes affecting financial products and capital-market transactions.
For taxpayers, the important lesson is that a tax rule applicable to an investment or financial transaction may have changed even when the transaction itself appears unchanged.
Where CMEPA fits in Philippine tax history
1997
RA 8424 — National Internal Revenue Code of 1997
2017
RA 10963 — TRAIN
2021
RA 11534 — CREATE
2024
RA 11976 — EOPT
2024
RA 12023 — VAT on Digital Services
2024
RA 12066 — CREATE MORE
2025
RA 12214 — CMEPA
RA 12214 was approved on May 29, 2025, and took effect on July 1, 2025, following its publication.
Its declaration of policy recognizes the importance of capital markets to economic growth and calls for a simpler, fairer, more efficient, and regionally competitive passive-income tax system.
CMEPA therefore belongs to a different reform emphasis from CREATE MORE. While CREATE MORE concentrates heavily on investment incentives for registered business enterprises, CMEPA focuses on the taxation of investment income, securities, and financial transactions.
What changed under CMEPA?
The law amended several NIRC provisions dealing with income taxation, capital gains, securities transactions, documentary stamp tax, and related matters.
The following are among its most significant changes:
Tax area | Principal change |
|---|---|
Stock Transaction Tax | Reduced from 0.6% to 0.1% |
Interest and similar passive income | Greater uniformity around the 20% rate, subject to exceptions |
Original issuance of shares | DST reduced from 1% to 0.75% |
Capital gains on certain shares | Expanded and revised treatment of domestic and foreign shares |
Certain financial instruments | Revised DST treatment and exemptions |
Retirement and investment savings | Changes affecting PERA-related tax treatment |
These changes are not all reductions. Some taxpayers benefit from lower transaction taxes, while certain previously preferentially taxed or exempt income becomes subject to a higher rate.
Stock Transaction Tax: from 0.6% to 0.1%
One of CMEPA’s most visible changes is the reduction in the Stock Transaction Tax (STT).
Under the revised Section 127 of the NIRC, the rate for covered transactions is 0.1% of the gross selling price or gross value in money, rather than the previous 0.6%.
ILLUSTRATIVE SALE OF COVERED LISTED SHARES
₱1,000,000
Gross selling price
Before CMEPA · 0.6%
₱6,000
Under CMEPA · 0.1%
₱1,000
Difference
₱5,000
This is significant because STT is computed on the gross selling price, not merely on the investor’s net profit.
CMEPA also extends the relevant STT framework to covered domestic shares listed and traded through a foreign stock exchange.
Legal basis: NIRC Section 127, as amended by RA 12214; RR No. 20-2025. The Philippine Stock Exchange confirmed implementation of the 0.1% rate beginning July 1, 2025.
Interest income: why the type of deposit still matters
Before CMEPA, different forms of deposit interest and investment income could receive different tax treatment.
For example, qualifying long-term deposits historically enjoyed preferential treatment, while certain foreign-currency deposit interest was taxed at a lower rate than ordinary peso-deposit interest.
CMEPA moved toward a more uniform 20% final income tax for covered interest, yield, and similar monetary benefits, regardless of currency or tenure, subject to statutory exceptions and transition provisions.
This means that the mere description of a product as a long-term deposit does not automatically establish that its interest remains tax-exempt under the post-CMEPA rules.
The tax treatment must be determined by reference to the applicable law, the instrument, the taxpayer’s classification, and the relevant transaction or issuance date.
Legal basis: NIRC Sections 24, 25, 27, and 28, as amended; RR No. 21-2025.
Documentary Stamp Tax: not every instrument is taxed alike
Documentary Stamp Tax (DST) is another important part of CMEPA.
The reform reduced the DST on the original issuance of shares from the equivalent of 1% to 0.75% of the relevant taxable base.
It also amended DST provisions affecting certain debt instruments, securities, and other financial documents, including specified exemptions.
This distinction is important:
DST on the issuance of shares is not the same tax as STT on the subsequent sale of covered listed shares.
A corporation issuing shares and an investor selling shares may encounter different taxable events, different statutory sections, and different compliance requirements.
Legal basis: NIRC Sections 174, 176, 179, 190, and 199, as amended by RA 12214; RR No. 19-2025.
Capital Gains Tax: domestic and foreign shares
CMEPA also revised the tax treatment of capital gains from shares of stock.
Under the amended Section 24(B)(3), a 15% final tax on net capital gains generally applies to covered sales, exchanges, or dispositions of shares in domestic or foreign corporations that are not traded through a local or foreign stock exchange.
Corresponding corporate provisions were also amended.
However, the taxpayer must distinguish between:
Shares subject to the Stock Transaction Tax;
Shares subject to the 15% final Capital Gains Tax;
Other securities or financial instruments whose gains may be subject to ordinary income tax; and
Transactions qualifying for exemptions or treaty benefits.
For example, the sale of unlisted shares and the sale of listed shares through a qualifying exchange are not automatically subject to the same tax.
The law also provides specific filing and payment rules for capital gains transactions.
Legal basis: NIRC Sections 24, 27, 28, 51, 52, and 56, as amended by RA 12214; RR No. 21-2025.
CMEPA also affects how investment income is classified
The reform is not limited to changing tax percentages.
RA 12214 revised statutory definitions relating to shares, shareholders, securities, deposit substitutes, and passive income.
It also addressed other matters, including equity-based compensation, gains from debt instruments, certain exclusions from gross income, and deductions associated with qualifying Personal Equity and Retirement Account (PERA) contributions.
This matters because the correct tax treatment begins with the legal classification of the transaction.
A payment described commercially as an investment return is not necessarily taxed in the same manner as a dividend, bank interest, capital gain, or ordinary business income.
Legal basis: NIRC Sections 22, 32, 34, 38, 39, and 42, as amended; RR Nos. 21-2025 and 22-2025.
The transition rules: why July 1, 2025 matters
One of the most important questions arising from tax-law amendments is:
Does the new tax treatment automatically apply to financial instruments that already existed before the law took effect?
Not necessarily.
CMEPA contains transition provisions affecting certain financial instruments issued or transacted before July 1, 2025.
For covered instruments, previously applicable exemptions or preferential rates may continue for the remaining maturity of the relevant agreement, subject to statutory conditions.
This means two taxpayers holding apparently similar financial products may encounter different tax treatments because the instruments were issued or transactions occurred on different dates.
The effective date of the law, the date of issuance, and the date income is earned must therefore be distinguished.
Legal basis: RA 12214, particularly its transitory provisions, and the applicable BIR regulations.
What about jurisprudence?
CMEPA is a relatively recent statute. Its provisions must be understood in light of established Philippine tax-law principles, without assuming that older decisions interpreting superseded statutory language automatically govern the amended rules.
Three principles are especially important.
First, taxes must have a statutory basis. Article VI, Section 28 of the 1987 Constitution provides the constitutional framework for taxation, including the rule on uniformity and equity.
Second, tax exemptions and preferential treatments depend on the governing law. Jurisprudence generally requires a clear legal basis for claimed tax exemptions, subject to the applicable rules of statutory construction.
Third, administrative issuances implement the law; they do not supersede it. Where a regulation conflicts with a statute, the statutory provision controls.
For this article, no specific Supreme Court ruling directly interpreting the principal CMEPA amendments has been independently established. Older jurisprudence should therefore be cited only for applicable general principles, not presented as a judicial interpretation of RA 12214 itself.
Why CMEPA matters to taxpayers and business owners
CMEPA is relevant beyond professional stock traders.
It can affect individuals maintaining financial investments, corporations issuing shares or debt instruments, shareholders disposing of investments, financial institutions, and employers making qualifying PERA contributions.
It also demonstrates that a reduction in one tax does not mean every related transaction has become less taxable.
The stock transaction tax decreased substantially. Certain documentary stamp taxes were reduced. At the same time, selected passive-income preferences were revised or removed.
A taxpayer who relies on a tax rate learned several years ago may therefore be applying a rule that no longer governs the transaction.
Legal references for further reading
The principal authorities for E-12 are:
Authority | Relevance |
|---|---|
1987 Constitution, Article VI, Section 28 | Constitutional taxation principles |
RA 8424, as amended | National Internal Revenue Code |
RA 12214 | Capital Markets Efficiency Promotion Act |
RR No. 19-2025 | DST amendments |
RR No. 20-2025 | Stock Transaction Tax |
RR No. 21-2025 | Income tax and passive-income provisions |
RR No. 22-2025 | PERA-related deductions |
RMC No. 61-2025 | Clarifications concerning repealed exemptions |
Official and primary-source references:
The lesson from CMEPA in Tax Code Evolution
CMEPA illustrates why Philippine tax law must be studied as an evolving legal system.
A transaction may have existed for decades, but the law governing it can change. A familiar tax rate may no longer apply. A previously exempt financial instrument may be subject to a new rule, while another transaction may benefit from a reduced tax.
Understanding Philippine tax law therefore requires more than identifying the original statute.
It requires understanding what the law originally provided, what subsequent legislation changed, which implementing rules apply, and which provisions govern the taxpayer’s actual transaction.
That is the continuing story of the National Internal Revenue Code.
Taxpayer Literacy is a Must!
This article is for general taxpayer education and does not constitute a transaction-specific tax opinion. The actual treatment depends on the taxpayer, financial instrument, transaction date, and applicable statutory or treaty provisions.
Related Philippine Tax Code Evolution Articles
[E-01] Before the NIRC: Where Did Philippine Tax Law Begin?
[E-02] From Act No. 1189 to Act No. 2339: How Philippine Internal Revenue Law Started To Evolve
[E-03] The Commonwealth Tax Code: How CA 466 Became the National Internal Revenue Code
[E-04] From CA 466 To PD 1158: Why the 1977 NIRC Was Another Recodification
[E-05] From The 1980s-1990s Tax Reforms To RA 8424: How the Modern NIRC Emerged
[E-06] The 1997 NIRC: How the Modern Philippine Tax Code Is Structured
[E-07] Train: Why RA 10963 Changed The 1997 NIRC
[E-08] Create: How RA 11534 Reshaped Corporate Taxation And Tax Incentives
[E-09] EOPT: Why RA 11976 Changed How Taxpayers Comply
[E-10] Digital Services VAT: How RA 12023 Brought Digital Services Into The Philippine Vat System
[E-11] Create More: Why RA 12066 Rewrote Parts Of The Create Framework
[E-12] CMEPA: How Ra 12214 Changed The Taxation Of Capital Markets And Financial Transactions
[E-13] The Current NIRC: How To Read The National Internal Revenue Code As Amended In 2026
[E-14] How A Philippine Tax Rule Is Born: From Legislation To Implementation
[E-15] How To Research Philippine Tax Law: Finding The Original Rule, Its Amendments, And The Current Legal Basis
Next:
[E-13]
THE CURRENT NIRC: HOW TO READ THE NATIONAL INTERNAL REVENUE CODE AS AMENDED IN 2026
The next article will bring together the major reforms covered in E-01 through E-12 and explain why the current NIRC cannot be understood simply by reading the original text of RA 8424.
Taxpayer Literacy is a Must!
Editorial Note
Current as of October 31, 2026.
This article is part of the Tax Code Evolution Series of easantoscpa.com Articles & Insights.
The purpose of this series is to help taxpayers understand where Philippine tax rules came from, how they evolved, and why today’s tax rules must be read together with their amendments, implementing issuances and jurisprudence.
Taxpayer Literacy is a Must!
Need Help With a Tax or Compliance Concern?
Understanding your obligations is the first step. Building the right compliance system is the next.
If your business needs professional guidance regarding BIR compliance, bookkeeping, documentation, tax concerns, or compliance review, you may discuss your specific circumstances with us.
BOOK A CONSULTATION →
Disclaimer
This article is provided for educational and conceptual purposes only and does not constitute tax, legal, accounting, or other professional advice. Tax rules and administrative requirements may change, and their application depends on the taxpayer’s particular facts and circumstances. Consult a qualified professional regarding your specific situation.
LEARN • STRENGTHEN • COMPLY
Trainings, Seminars & Webinars
Practical learning for business owners, professionals and teams.
- services@easantoscpa.com
- +63 916 587 1528
- Topaz Building, Kamias Road, Quezon City
- Office visit: By Appointment only.
- Strictly NO Walk-In
- Affiliate: ptabcpsolutions.com
Disclaimer: Posts are provided for educational and conceptual purposes only. They do not constitute professional advice. You are advised to consult a qualified professional regarding your specific circumstances.