[E-15] HOW TO RESEARCH PHILIPPINE TAX LAW: FINDING THE ORIGINAL RULE, ITS AMENDMENTS, AND THE CURRENT LEGAL BASIS
Tax Code Evolution Series No. 15
Why Finding the Latest BIR Issuance Is Not Always Enough to Understand the Applicable Tax Rule
Part I — Tax Code Evolution | easantoscpa.com
Last reviewed: October 31, 2026
You found a BIR issuance. But have you found the complete legal basis?
A business owner searches online for the proper tax treatment of a transaction.
The search produces a Revenue Memorandum Circular. It appears relevant, contains official BIR language, and discusses the taxpayer’s concern.
The business owner concludes:
“Ito na siguro ang applicable rule.”
But several questions remain.
Was the circular interpreting a provision of the National Internal Revenue Code? Was that provision subsequently amended? Was the circular explaining a Revenue Regulation that has since been revised? Did the issuance apply only to certain taxpayers, transactions, or periods?
And has the Supreme Court already interpreted the relevant statutory provision?
These questions matter because finding a tax issuance is not necessarily the same as identifying the complete legal rule.
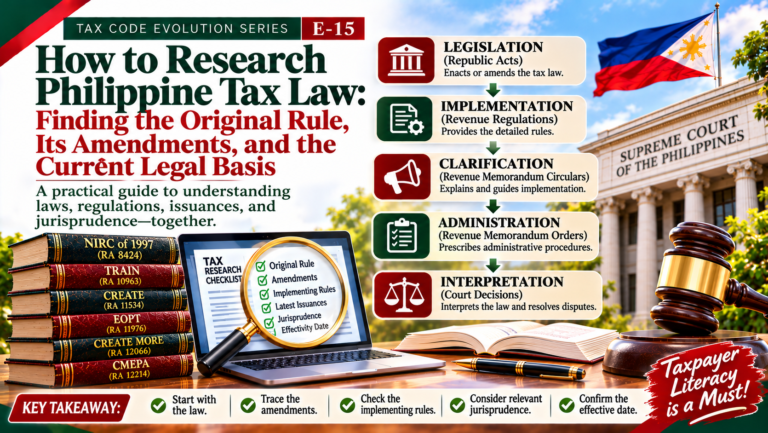
Philippine tax law develops through legislation, implementing regulations, administrative guidance, and judicial decisions.
Understanding the relationship among these authorities is an important part of taxpayer literacy.
This final article in the Tax Code Evolution Series explains the legal sources that taxpayers may encounter and why the original rule, subsequent amendments, effective dates, and current interpretation must be distinguished.
Philippine tax law is not contained in a single document
The National Internal Revenue Code of 1997, enacted through Republic Act No. 8424, is the central statutory framework for Philippine national internal revenue taxation.
However, RA 8424 has been amended repeatedly.
TRAIN, CREATE, EOPT, the Digital Services VAT law, CREATE MORE, and CMEPA are among the major reforms discussed in the preceding articles of this series.
In addition, the Department of Finance and the BIR issue implementing regulations and administrative guidance.
Courts interpret statutes and resolve disputes concerning their application.
Consequently, the applicable tax rule may require consideration of several legal sources rather than one document.
A useful distinction is between the source of the tax obligation and the administrative rules governing its implementation.
Understanding the different sources of tax authority
Source | Principal function |
|---|---|
1987 Constitution | Establishes constitutional authority and limitations |
Republic Acts and other valid statutes | Enact or amend substantive tax law |
Revenue Regulations (RRs) | Implement statutes under delegated authority |
Revenue Memorandum Circulars (RMCs) | Publish or clarify interpretations and guidance |
Revenue Memorandum Orders (RMOs) | Prescribe administrative policies and procedures |
BIR Rulings | Address particular legal questions or factual circumstances |
Court decisions | Interpret law and resolve justiciable controversies |
These authorities are not interchangeable.
An RMC may explain the BIR’s interpretation of a statutory requirement. An RMO may establish administrative procedures for implementing an audit program. A Revenue Regulation may prescribe implementing rules under the authority of the NIRC.
But none of these issuances can validly override a controlling statute.
The distinction is supported by NIRC Sections 4, 244, and 245, which address the Commissioner’s interpretative powers and the authority to promulgate implementing regulations.
The original rule: where did the obligation begin?
Consider a question concerning invoices.
A taxpayer may encounter an invoicing regulation issued in 2024, 2025, or 2026.
But the legal foundation may be found in provisions of the NIRC that originated earlier and were subsequently amended by EOPT.
The original statutory provisions remain important because they establish the history and legal character of the obligation.
However, the original version does not necessarily determine the current requirements.
For example, the NIRC’s invoicing provisions have evolved through statutory amendments and implementing issuances.
This is why the original rule provides historical context, while the applicable amended provision determines the current statutory requirement.
The same principle applies to income tax rates, VAT, withholding obligations, deductions, exemptions, and taxpayer remedies.
Amendments: why an older rule may no longer be applicable
A statute may be amended expressly, and an implementing regulation may be revised, supplemented, or superseded.
For example, the BIR issued RR No. 6-2026 to amend the mandatory invoice information prescribed under RR No. 7-2024. Subsequently, RMC No. 112-2026 provided clarification and transitional guidance concerning the separate presentation of creditable withholding tax on invoices.
This example demonstrates that the development of a compliance requirement may involve several related issuances.
A reader who examines RR No. 7-2024 without considering subsequent amendments may overlook requirements introduced later.
Conversely, a reader who sees only RMC No. 112-2026 may miss the underlying statutory and regulatory context.
The issue is not merely which document is newest.
It is which documents remain legally relevant and how they relate to one another.
Effectivity: the latest rule may not govern an earlier transaction
Suppose a taxpayer encounters a 2026 issuance concerning a transaction completed in 2024.
Can the 2026 issuance automatically determine the taxpayer’s obligation?
Not necessarily.
The relevant considerations include whether the issuance is substantive or interpretative, its effective date, the applicable statutory provisions, and any transitional arrangements.
Article 4 of the Civil Code provides the general principle that laws do not have retroactive effect unless otherwise provided.
Article 2, as amended by Executive Order No. 200, governs the general framework for publication and effectivity.
In Tañada v. Tuvera, G.R. No. L-63915, December 29, 1986, the Supreme Court emphasized publication requirements for laws and administrative regulations intended to enforce or implement existing laws.
The NIRC also contains a specific protection under Section 246 concerning the prejudicial retroactive application of revoked, modified, or reversed regulations, rulings, and circulars, subject to statutory exceptions involving material misstatements, materially different facts, or bad faith.
Thus, identifying the latest issuance is only part of understanding the applicable rule.
Jurisprudence: how court decisions affect tax-law interpretation
Court decisions are another essential component of Philippine tax-law research.
A Supreme Court decision may explain the meaning of a statutory provision, clarify procedural requirements, or determine whether an administrative issuance is valid.
But jurisprudence must be understood in context.
A decision interpreting a provision before a statutory amendment may not necessarily govern the amended provision in exactly the same way.
For example, jurisprudence concerning tax refund procedures under an earlier version of the NIRC must be examined in light of subsequent legislative amendments, including those introduced by EOPT.
This does not mean older decisions automatically become irrelevant.
Some continue to establish important principles concerning statutory construction, administrative authority, due process, and taxpayer rights.
The relevant question is whether the particular judicial principle remains applicable to the statutory language and circumstances being examined.
A Philippine example: electronic invoicing
Electronic invoicing illustrates how multiple authorities can operate together.
The NIRC provides the statutory foundation for invoicing and related compliance requirements.
TRAIN introduced Section 237-A concerning electronic sales reporting. EOPT subsequently amended important provisions relating to invoicing and tax administration.
The BIR then issued implementing regulations and guidance addressing electronic invoicing requirements.
In September 2026, RMC No. 98-2026 prescribed policies and guidelines on the issuance of electronic invoices under RR No. 8-2022 and RR No. 11-2025, as amended by RR No. 26-2025.
A taxpayer who examines only RMC No. 98-2026 may understand certain current administrative requirements but not necessarily the complete legislative development of electronic invoicing.
Likewise, a taxpayer who reads only the original Section 237-A may not understand how subsequent regulations affect particular businesses.
The complete legal context therefore involves both the statutory foundation and the applicable implementing framework.
Why administrative procedures also require current references
Some tax developments concern not the creation of a new tax but changes in administrative procedures.
For example, RMO No. 17-2026 updated policies and procedures for processing certain One-Time Transactions involving sales and donations of property.
RMO No. 25-2026 amended earlier procedures for processing specified tax-credit and refund claims.
Bureau of Internal Revenue
These issuances illustrate a distinction between:
Substantive tax law, which establishes the legal tax treatment, and administrative procedure, which governs how the relevant obligation or claim is processed.
Both may matter to taxpayers.
However, changes in administrative procedures should not automatically be described as amendments to the statutory tax itself.
Official sources and the reliability of tax information
Taxpayers frequently encounter tax information through social media, search engines, accounting websites, training materials, and professional commentary.
These sources may be useful for awareness and understanding.
However, summaries can omit exceptions, transitional provisions, amendments, or important factual qualifications.
Official legal texts and issuances provide the foundation for determining the applicable rule.
Useful starting points include:
Even when using an official source, the reader should distinguish an original statute from a consolidated text and determine whether the consolidation incorporates subsequent amendments.
A publication date, approval date, effectivity date, and transaction date may all be legally significant.
Common misunderstandings about Philippine tax research
Common assumption | What taxpayers should understand |
|---|---|
“Nasa BIR website, so complete na.” | An official document may still need to be read alongside amendments and related issuances. |
“Latest RMC ang nakita ko, so iyon na ang buong rule.” | A circular may clarify only part of a broader statutory and regulatory framework. |
“Pareho ang section number, so pareho ang provision.” | A section may have been amended without changing its number. |
“May bagong RR, so may bagong tax.” | A regulation may implement an existing statutory obligation rather than create a new tax. |
“May Supreme Court decision na, so applicable forever.” | Later statutory amendments or factual distinctions may affect the decision’s application. |
“Ganito ang practice namin noon, so compliant pa rin ngayon.” | Administrative and statutory requirements |
The importance of understanding legal authority
The distinction among statutes, regulations, administrative issuances, and jurisprudence is more than an academic concern.
It affects how taxpayers understand their obligations and rights.
An incorrect interpretation may result in an inappropriate tax treatment, inadequate documentation, missed requirements, or reliance on a procedure that is no longer applicable.
On the other hand, understanding the legal foundation of a requirement allows taxpayers to recognize that tax compliance involves more than following an instruction without knowing its source.
The goal is not to turn every business owner into a lawyer or tax specialist.
It is to develop sufficient awareness to appreciate that tax rules have legal origins, amendments, effective dates, limitations, and interpretations.
That understanding helps taxpayers ask better questions and recognize when a transaction requires further professional examination.
Legal basis and jurisprudence
The principal authorities relevant to this article include:
Authority | Relevance |
|---|---|
1987 Constitution, Article VI, Section 28 | Constitutional taxation principles |
1987 Constitution, Article VIII, Section 1 | Judicial power |
Civil Code, Articles 2 and 4 | Effectivity and nonretroactivity |
EO No. 200 (1987) | Amendment of Civil Code Article 2 |
RA 8424, as amended | National Internal Revenue Code |
NIRC Section 4 | Commissioner’s interpretative authority |
NIRC Sections 244–245 | Implementing regulations |
NIRC Section 246 | Nonretroactivity of rulings |
Tañada v. Tuvera, G.R. No. L-63915 | Publication of laws and implementing rules |
CIR v. Fortune Tobacco Corporation, G.R. Nos. 167274–75 | Limits of administrative regulations |
CIR v. San Roque Power Corporation, G.R. No. 187485 and companion cases | Statutory interpretation and administrative guidance |
These authorities establish general principles. Their application to a particular taxpayer or dispute requires consideration of the governing facts and currently operative law.
The final lesson of the Tax Code Evolution Series
The Philippine tax system has undergone substantial changes since the earliest internal revenue laws.
From Act No. 1189, through the consolidation of internal revenue legislation, the 1939 and 1977 Codes, the 1997 NIRC, and subsequent reforms such as TRAIN, CREATE, EOPT, CREATE MORE, and CMEPA, the legal framework has continued to evolve.
The evolution has not stopped.
New legislation, implementing regulations, administrative guidance, and court decisions continue to shape the obligations and rights of taxpayers.
The most important lesson from this series is therefore not simply the history of Philippine taxation.
It is this:
Knowing the original law is important. Knowing how it evolved is equally important. Knowing which rule applies to the taxpayer’s actual transaction is essential.
A tax provision should not be understood solely by its section number. An administrative issuance should not be treated as though it exists independently of its statutory foundation. A court decision should not be read without considering the law and facts it interpreted.
And a familiar business practice should not be assumed compliant merely because it was acceptable in an earlier period.
Taxpayer Literacy is a Must!
This article is intended for general Philippine tax education. It is not a substitute for a legal opinion or transaction-specific professional advice. Tax laws and administrative issuances should be evaluated according to their applicability and effective dates.
Related Philippine Tax Code Evolution Articles
[E-01] Before the NIRC: Where Did Philippine Tax Law Begin?
[E-02] From Act No. 1189 to Act No. 2339: How Philippine Internal Revenue Law Started To Evolve
[E-03] The Commonwealth Tax Code: How CA 466 Became the National Internal Revenue Code
[E-04] From CA 466 To PD 1158: Why the 1977 NIRC Was Another Recodification
[E-05] From The 1980s-1990s Tax Reforms To RA 8424: How the Modern NIRC Emerged
[E-06] The 1997 NIRC: How the Modern Philippine Tax Code Is Structured
[E-07] Train: Why RA 10963 Changed The 1997 NIRC
[E-08] Create: How RA 11534 Reshaped Corporate Taxation And Tax Incentives
[E-09] EOPT: Why RA 11976 Changed How Taxpayers Comply
[E-10] Digital Services VAT: How RA 12023 Brought Digital Services Into The Philippine Vat System
[E-11] Create More: Why RA 12066 Rewrote Parts Of The Create Framework
[E-12] CMEPA: How Ra 12214 Changed The Taxation Of Capital Markets And Financial Transactions
[E-13] The Current NIRC: How To Read The National Internal Revenue Code As Amended In 2026
[E-14] How A Philippine Tax Rule Is Born: From Legislation To Implementation
[E-15] How To Research Philippine Tax Law: Finding The Original Rule, Its Amendments, And The Current Legal Basis
Editorial Note
Current as of October 31, 2026.
This article is part of the Tax Code Evolution Series of easantoscpa.com Articles & Insights.
The purpose of this series is to help taxpayers understand where Philippine tax rules came from, how they evolved, and why today’s tax rules must be read together with their amendments, implementing issuances and jurisprudence.
Taxpayer Literacy is a Must!
Need Help With a Tax or Compliance Concern?
Understanding your obligations is the first step. Building the right compliance system is the next.
If your business needs professional guidance regarding BIR compliance, bookkeeping, documentation, tax concerns, or compliance review, you may discuss your specific circumstances with us.
BOOK A CONSULTATION →
Disclaimer
This article is provided for educational and conceptual purposes only and does not constitute tax, legal, accounting, or other professional advice. Tax rules and administrative requirements may change, and their application depends on the taxpayer’s particular facts and circumstances. Consult a qualified professional regarding your specific situation.
LEARN • STRENGTHEN • COMPLY
Trainings, Seminars & Webinars
Practical learning for business owners, professionals and teams.
- services@easantoscpa.com
- +63 916 587 1528
- Topaz Building, Kamias Road, Quezon City
- Office visit: By Appointment only.
- Strictly NO Walk-In
- Affiliate: ptabcpsolutions.com
Disclaimer: Posts are provided for educational and conceptual purposes only. They do not constitute professional advice. You are advised to consult a qualified professional regarding your specific circumstances.