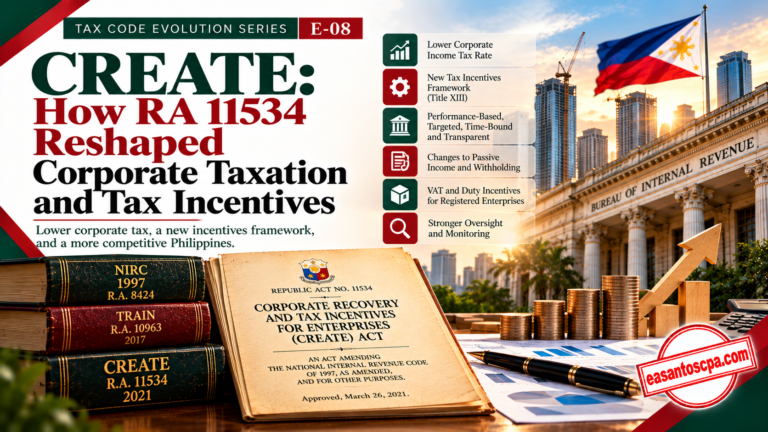
[E-08] CREATE: HOW RA 11534 RESHAPED CORPORATE TAXATION AND TAX INCENTIVES
Tax Code Evolution Series No. 8
CREATE did more than lower corporate income tax. It changed the architecture of corporate taxation and tax incentives in the Philippines.
When TRAIN became law in 2017, it significantly changed the individual-tax side of the Philippine tax system.
But the next major reform addressed another major part of the NIRC:
corporate taxation and fiscal incentives.
That reform was Republic Act No. 11534, known as the Corporate Recovery and Tax Incentives for Enterprises Act, or CREATE.
Approved on March 26, 2021, CREATE amended numerous provisions of the 1997 NIRC and created an entirely new Title XIII — Tax Incentives.
And there is an important reason why CREATE belongs in the Tax Code Evolution Series:
It changed not only how corporations are taxed, but also how the government designs, grants, monitors and limits tax incentives.
Why did CREATE happen?
CREATE was enacted during a very unusual period.
The Philippines—and the rest of the world—was dealing with the economic effects of the COVID-19 pandemic.
CREATE therefore had two related objectives.
First:
help businesses recover.
Second:
reform the corporate tax and investment-incentive system.
The law itself states that the State sought to:
- improve the equity and efficiency of the corporate tax system;
- lower the corporate tax rate;
- widen the tax base;
- reduce tax distortions and leakages;
- develop a more competitive incentives regime;
- make incentives performance-based, targeted, time-bound and transparent; and
- support businesses affected by unforeseen events such as the pandemic.
So CREATE was both a corporate tax reform and an investment-policy reform.
CREATE did not replace the NIRC
Just like TRAIN, CREATE did not create a completely new Tax Code.
Instead, RA 11534 expressly amended provisions of the:
National Internal Revenue Code of 1997, as amended.
CREATE amended, among others:
- Sections 20;
- 22;
- 25;
- 27;
- 28;
- 29;
- 34;
- 40;
- 57;
- 109;
- 116;
- 204; and
It also created a new Title XIII — Tax Incentives.
The evolution therefore continued:
PD 1158 — 1977 NIRC
↓
RA 8424 — 1997 NIRC
↓
RA 10963 — TRAIN
↓
RA 11534 — CREATE
↓
RA 11976 — EOPT
↓
RA 12023 — Digital Services VAT
↓
RA 12066 — CREATE MORE
↓
RA 12214 — CMEPA
↓
Current NIRC, as amended
This sequence is important.
CREATE must be understood as one major layer of amendments, not as the entire current corporate-tax law.
The headline change: corporate income tax was reduced
One of CREATE’s most visible reforms was the reduction of the regular corporate income-tax rate.
For domestic corporations, CREATE amended Section 27 of the NIRC to provide for a 25% regular corporate income-tax rate, effective July 1, 2020.
It also introduced a 20% rate for qualifying corporations with:
- net taxable income not exceeding ₱5 million, and
- total assets not exceeding ₱100 million, excluding the land on which the business’s office, plant and equipment are situated.
This was a major change from the previous general corporate income-tax rate.
But notice something important:
The effective date preceded the date CREATE was signed.
CREATE was signed into law in 2021, but certain corporate-tax provisions were made effective July 1, 2020.
That is an excellent example of why tax research cannot rely solely on:
“When was the law enacted?”
The researcher must also ask:
“When did the particular provision become effective?”
CREATE also reduced the Minimum Corporate Income Tax
CREATE also changed the Minimum Corporate Income Tax (MCIT).
The regular MCIT framework remained, but CREATE temporarily reduced the rate from 2% to 1% for the period beginning July 1, 2020 through June 30, 2023.
This was part of CREATE’s pandemic-era relief measures.
This is another useful research lesson:
Some tax reforms are permanent structural changes; others are temporary relief measures.
You therefore cannot assume that every provision introduced by a major tax law continues indefinitely.
The applicable tax year and effective period matter.
CREATE also changed taxation of foreign corporations
CREATE amended Section 28 concerning foreign corporations.
For example, the regular income-tax rate for a resident foreign corporation engaged in trade or business in the Philippines was reduced to 25%, effective July 1, 2020.
CREATE also made changes affecting:
- nonresident foreign corporations;
- branch profits;
- passive income;
- intercorporate dividends; and
- capital gains involving shares of stock.
These provisions demonstrate why corporate taxation cannot be reduced to one question:
“What is the corporate tax rate?”
The correct rate can depend on:
- whether the entity is domestic or foreign;
- whether a foreign corporation is resident or nonresident;
- the type of income;
- the source of income;
- whether the income is active or passive; and
- whether a special regime applies.
CREATE changed certain passive-income rules
CREATE also amended the treatment of certain passive income.
For example, it changed provisions involving:
- dividends;
- interest;
- royalties;
- capital gains from shares of stock not traded through the stock exchange; and
- foreign-sourced dividends received by domestic corporations.
One important reform was the treatment of qualifying foreign-sourced dividends received by domestic corporations.
CREATE provided conditions under which such dividends could qualify for exemption, including requirements involving:
- reinvestment in Philippine business operations; and
- minimum ownership and holding periods.
This reflects a broader policy direction:
The tax system can be designed not only to collect tax, but also to encourage reinvestment and economic activity.
But CREATE’s bigger story is tax incentives
If corporate income-tax reduction were the only thing CREATE did, it would already be significant.
But its more transformative feature was Title XIII — Tax Incentives.
CREATE effectively placed a statutory framework around the granting and administration of tax incentives.
The law expressly stated that the incentives regime should be:
performance-based, targeted, time-bound and transparent.
That is a very different way of thinking about tax incentives.
Instead of:
“A business is located in a special zone, therefore it receives a broad tax privilege.”
the policy direction became closer to:
“What project is being registered, what economic activity does it perform, what incentives does the law authorize, and what conditions must the enterprise satisfy?”
CREATE created Title XIII of the NIRC
CREATE inserted an entirely new Title XIII — Tax Incentives into the NIRC.
This was a major structural development.
The new framework addressed:
- registered business enterprises;
- investment promotion agencies;
- tax incentives;
- the Fiscal Incentives Review Board;
- strategic investment priorities;
- income-tax holidays;
- special corporate income tax;
- enhanced deductions;
- VAT and duty incentives;
- conditions for availment;
- periods of availment;
- monitoring and evaluation; and
- transitory rules for existing enterprises.
In other words:
Tax incentives became more explicitly integrated into the architecture of the NIRC itself.
What kinds of incentives did CREATE provide?
CREATE inserted an entirely new Title XIII — Tax Incentives into the NIRC.
This was a major structural development.
The new framework addressed:
- registered business enterprises;
- investment promotion agencies;
- tax incentives;
- the Fiscal Incentives Review Board;
- strategic investment priorities;
- income-tax holidays;
- special corporate income tax;
- enhanced deductions;
- VAT and duty incentives;
- conditions for availment;
- periods of availment;
- monitoring and evaluation; and
- transitory rules for existing enterprises.
In other words:
Tax incentives became more explicitly integrated into the architecture of the NIRC itself.
What kinds of incentives did CREATE provide?
Under the original CREATE framework, registered projects or activities could potentially receive several types of incentives.
Among them were:
Income Tax Holiday — ITH
An exemption from income tax on the registered project or activity for the qualified period.
Special Corporate Income Tax — SCIT
For qualified enterprises, CREATE provided a special corporate income-tax regime based on gross income earned, subject to statutory conditions.
Enhanced Deductions
CREATE also introduced additional deductions for qualified expenditures.
These included additional deductions involving areas such as:
- labor expense;
- research and development;
- training;
- domestic inputs;
- power;
- depreciation; and
- other qualified expenditures.
The original CREATE law also provided:
- duty exemption on certain imports; and
- VAT exemption/zero-rating privileges subject to the statutory requirements.
CREATE made incentives conditional
This is one of the most important concepts for businesses receiving incentives.
A tax incentive is not necessarily a blanket privilege.
CREATE established conditions for availment.
For example, incentives were tied to the:
- registered project or activity;
- approved registration;
- applicable investment-promotion framework;
- Strategic Investment Priority Plan;
- performance requirements; and
- statutory period of availment.
The law also empowered the Fiscal Incentives Review Board (FIRB) with expanded oversight functions.
The FIRB’s functions included matters such as:
- policy-making and oversight;
- setting performance metrics;
- monitoring and evaluation;
- reviewing compliance;
- cost-benefit analysis; and
- approval or delegated approval of incentives.
This is significant.
CREATE moved tax incentives further away from the idea of an automatic entitlement and toward a system of regulated, monitored fiscal support.
Why did CREATE create the FIRB framework?
The policy question was straightforward:
If the government gives up tax revenue through incentives, how does it know whether the incentive is actually producing the economic benefit intended?
CREATE’s answer was to strengthen institutional oversight.
The law gave the FIRB an expanded role in:
granting → monitoring → evaluating → reviewing
tax incentives.
That is why the law’s language emphasized:
performance-based
and
transparent
incentives.
The incentive is therefore connected to a policy objective—not merely to the taxpayer’s desire to reduce tax.
CREATE also changed the VAT environment for incentivized enterprises
This is where corporate tax and transaction-level tax compliance intersect.
CREATE included rules concerning VAT exemption on importation and VAT zero-rating on certain local purchases of qualified registered business enterprises.
But the actual operation of these provisions became the subject of subsequent:
- Revenue Regulations;
- Revenue Memorandum Circulars;
- implementing rules; and
- litigation.
The BIR, for example, issued RR No. 21-2021 implementing relevant VAT provisions under CREATE.
The resulting rules distinguished between registered export enterprises (REEs) and domestic market enterprises (DMEs) in the treatment of certain VAT zero-rating benefits.
This became a practical compliance issue for businesses operating inside economic zones and other investment-promotion environments.
And this is where CREATE becomes a jurisprudence story
A particularly useful modern case is:
Subic Bay Freeport Chamber of Commerce, Inc. and Benjamin E. Antonio III v. Department of Finance, et al.
G.R. No. 266016, February 4, 2025
The case involved the CREATE framework and the VAT treatment of purchases by registered business enterprises.
The petitioners challenged portions of the CREATE implementing framework and BIR issuances that limited certain VAT zero-rating benefits to registered export enterprises.
The Supreme Court’s decision is useful for understanding a larger principle:
A taxpayer’s registration under an incentive regime does not automatically answer every tax question.
The taxpayer still has to examine:
- what type of registered business enterprise it is;
- what project or activity is registered;
- what incentive was granted;
- what statutory conditions apply;
- what implementing rules govern the incentive; and
- whether the particular purchase or transaction falls within the statutory scope.
This is precisely why tax incentive compliance is not simply “We are PEZA/BOI/eco-zone registered.”
Tax incentives are strictly construed
Philippine jurisprudence has long established an important rule:
Tax exemptions are not presumed.
Because taxation is the rule and exemption is the exception, an exemption or tax privilege must generally be supported by clear statutory language.
The Supreme Court has repeatedly applied this principle. In CIR v. CA / related tax-exemption jurisprudence, the Court has explained that tax exemptions are construed strictissimi juris against the taxpayer claiming the exemption.
A more recent illustration is Thunderbird Pilipinas Hotels and Resorts, Inc. v. CIR, G.R. No. 211327, November 11, 2020, where the Supreme Court strictly construed the statutory language granting a particular tax exemption.
This principle is extremely important when dealing with CREATE incentives.
A taxpayer should not begin with:
“What tax exemption can I claim?”
The better question is:
“What exact statutory provision grants this incentive, and do the facts satisfy its conditions?”
CREATE also teaches us the importance of implementing regulations
CREATE was not implemented by simply reading RA 11534.
The BIR issued multiple regulations.
Among the significant 2021 issuances were:
- RR No. 2-2021 — passive-income provisions;
- RR No. 3-2021 — Section 20 information provisions;
- RR No. 4-2021 — VAT and percentage tax provisions;
- RR No. 5-2021 — corporate income-tax rates and certain deductions; and
- RR No. 21-2021 — VAT exemption/zero-rating provisions for registered business enterprises.
This is another demonstration of the research chain:
Republic Act
↓
NIRC provision as amended
↓
Revenue Regulation
↓
RMC/RMO and other administrative guidance
↓
Actual taxpayer transaction
A researcher who stops at the Republic Act may not yet have the complete operational picture.
CREATE also produced transition problems
CREATE changed the incentive system, but thousands of businesses were already operating under earlier incentive regimes.
What happens to them?
CREATE therefore contained transitory provisions.
For example, registered business enterprises already enjoying certain incentives before CREATE’s effectivity were given rules concerning the continuation and transition of their existing incentives.
This created an important legal question:
Which rules apply to an enterprise that entered an incentive regime before CREATE but continues operating after CREATE?
The answer may depend on:
- date of registration;
- certificate of registration;
- specific incentive granted;
- remaining incentive period;
- CREATE’s transitory provisions;
- implementing regulations; and
- later amendments.
This is a classic example of why tax-law evolution matters to actual taxpayers.
CREATE did not remain untouched
Here is the most important current-law warning.
Just as TRAIN was subsequently modified, CREATE itself was later amended.
The major amendment was:
RA 12066 — CREATE MORE
Approved in 2024, CREATE MORE further amended numerous provisions of the NIRC relating to:
- corporate income tax;
- VAT;
- registered business enterprises;
- tax incentives;
- income tax holiday;
- special corporate income tax;
- enhanced deductions;
- incentive periods;
- transition rules; and
- related provisions.
So if a taxpayer today says:
“Under CREATE, the incentive is…”
that statement may still be incomplete.
The researcher must ask:
“Do you mean the original CREATE framework under RA 11534, or CREATE as subsequently amended by CREATE MORE?”
CREATE MORE changed the incentive architecture again
Under the current amended framework, CREATE MORE modified the incentive structure.
For example, the amended Section 294 recognizes:
- Income Tax Holiday (ITH);
- Special Corporate Income Tax (SCIT);
- Enhanced Deductions Regime (EDR);
- and other statutory incentives.
CREATE MORE also changed the periods and conditions for incentive availment and made significant modifications concerning registered export enterprises and domestic market enterprises.
This is why a 2021 article describing CREATE cannot simply be copied into a 2026 compliance manual.
The history remains useful, but the operative rule must be updated.
Even VAT treatment under the incentive regime continues to evolve
The evolution did not stop with CREATE MORE.
For example, the BIR issued RR No. 9-2025 implementing provisions of Section 295(D), as amended by CREATE MORE, concerning local sales by registered business enterprises.
The BIR subsequently issued RR No. 1-2026, further clarifying and amending rules involving:
- VAT on local sales;
- optional VAT registration for certain RBEs;
- system reconfiguration;
- exclusions from the VAT-on-local-sales framework; and
- related matters.
This is a perfect real-life example of our central Tax Code Evolution principle:
A major tax law may create the framework. Later laws and administrative issuances determine how that framework operates today.
The taxpayer lesson: corporate tax is not just a rate
A corporation might ask:
“What is my corporate income-tax rate?”
That is only the beginning.
The researcher may need to determine:
First:
What kind of corporation is it?
Second:
What kind of income does it earn?
Third:
Is it domestic or foreign?
Fourth:
Does it qualify for a special tax treatment?
Fifth:
Is it a registered business enterprise?
Sixth:
What project or activity is registered?
Seventh:
What incentive regime applies?
Eighth:
What law was effective during the relevant period?
Ninth:
What implementing regulations apply?
Tenth:
Were the CREATE provisions later amended by CREATE MORE or another statute?
That is why corporate tax research is not simply rate lookup.
A simple example
Imagine a corporation tells its tax adviser:
“We are registered in an economic zone, so all our purchases are VAT zero-rated and we pay only 5% tax.”
That statement contains several separate legal questions.
The adviser must determine:
- when the corporation registered;
- with which investment promotion agency;
- whether it is an export enterprise or domestic market enterprise;
- what project or activity was registered;
- what incentive regime applies;
- whether the enterprise is still within its incentive period;
- whether the particular purchase is directly attributable to the registered activity;
- what VAT rule applies to that transaction;
- what documentation is required; and
- what current law and implementing regulations govern the transaction.
The words:
“We are ecozone registered.”
do not, by themselves, resolve the tax treatment.
The bigger lesson from CREATE
TRAIN taught us:
A major tax law can change many provisions of the NIRC without replacing the NIRC itself.
CREATE adds another lesson:
A tax incentive is not merely a tax break. It is a statutory policy instrument with conditions, limitations, monitoring and an intended economic purpose.
This is especially important for businesses.
Tax incentives affect:
- pricing;
- investment decisions;
- accounting;
- tax provisioning;
- VAT treatment;
- documentation;
- reporting;
- corporate structuring;
- compliance monitoring; and
- long-term business planning.
A business that qualifies for an incentive therefore needs more than a certificate.
It needs to understand the legal conditions attached to that incentive.
LEGAL BASIS
Constitutional foundation
1987 Philippine Constitution
Particularly relevant:
- Article VI, Section 28(1) — uniform and equitable taxation and the progressive-taxation mandate;
- Article VI, Section 28(2) — authority concerning tariff and taxation-related delegation within constitutional limits;
- Article III, Section 1 — due process and equal protection.
Principal statute
Republic Act No. 11534 — Corporate Recovery and Tax Incentives for Enterprises Act (CREATE)
Approved: March 26, 2021
CREATE amended numerous provisions of RA 8424, the NIRC of 1997, as amended, and inserted Title XIII — Tax Incentives.
Important implementing issuances
Among the principal CREATE-era BIR regulations were:
- RR No. 2-2021
- RR No. 3-2021
- RR No. 4-2021
- RR No. 5-2021
- RR No. 21-2021
Subsequent major amendment
Republic Act No. 12066 — CREATE MORE Act
RA 12066 further amended numerous NIRC provisions relating to corporate taxation and tax incentives.
Current implementing developments
The CREATE MORE framework has continued to generate implementing issuances, including:
- RR No. 9-2025 on local sales by RBEs; and
- RR No. 1-2026 further amending and clarifying VAT rules affecting RBEs.
Jurisprudence
Subic Bay Freeport Chamber of Commerce, Inc. v. Department of Finance, et al.
G.R. No. 266016, February 4, 2025
Important because it directly involved the CREATE incentive framework and the VAT treatment of registered business enterprises. The case illustrates the importance of distinguishing the statutory text from implementing rules and examining the precise scope of an incentive.
Thunderbird Pilipinas Hotels and Resorts, Inc. v. Commissioner of Internal Revenue
G.R. No. 211327, November 11, 2020
Important for the broader principle that statutory tax exemptions must be construed strictly according to the language granting the exemption.
Long-standing Supreme Court rule
The Court has repeatedly held that:
tax exemptions are not presumed and must be clearly established by law.
That principle remains highly relevant when analyzing CREATE incentives.
What should taxpayers remember?
If you remember only six things about CREATE:
1. CREATE amended the 1997 NIRC.
It did not replace the NIRC with an entirely new Tax Code.
2. CREATE reduced the regular corporate income-tax rate.
But the applicable rate depends on the taxpayer and applicable statutory conditions.
3. CREATE introduced a major new tax-incentive framework.
It inserted Title XIII — Tax Incentives into the NIRC.
4. Tax incentives come with conditions.
Registration alone does not necessarily establish entitlement to every tax privilege.
5. CREATE has already been amended.
CREATE MORE / RA 12066 substantially modified the corporate tax and incentive framework.
6. Current tax research must go beyond CREATE.
The correct question is not:
“What did CREATE say?”
It is:
“What does the NIRC provision say today, as amended by CREATE, CREATE MORE and subsequent laws and implemented by current BIR rules?”
The Tax Code Evolution Lesson
At this point in our journey, the evolution becomes clearer:
1997 NIRC
gave us the reorganized statutory framework.
TRAIN
substantially changed individual taxation and other major tax provisions.
CREATE
restructured corporate taxation and tax incentives.
CREATE MORE and later laws
continued modifying that structure.
Therefore:
Philippine tax law is not a collection of isolated tax laws. It is an evolving legal system.
And when researching a tax issue, the real question is rarely:
“What does this law say?”
The better question is:
“Where did this rule come from, what changed it, what implements it, what interpreted it, and what is the operative rule today?”
That is the habit of proper Philippine tax-law research.
Related Philippine Tax Code Evolution Articles
[E-01] Before the NIRC: Where Did Philippine Tax Law Begin?
[E-02] From Act No. 1189 to Act No. 2339: How Philippine Internal Revenue Law Started To Evolve
[E-03] The Commonwealth Tax Code: How CA 466 Became the National Internal Revenue Code
[E-04] From CA 466 To PD 1158: Why the 1977 NIRC Was Another Recodification
[E-05] From The 1980s-1990s Tax Reforms To RA 8424: How the Modern NIRC Emerged
[E-06] The 1997 NIRC: How the Modern Philippine Tax Code Is Structured
[E-07] Train: Why Ra 10963 Changed The 1997 NIRC
E-08] Create: How RA 11534 Reshaped Corporate Taxation And Tax Incentives
[E-09] EOPT: Why RA 11976 Changed How Taxpayers Comply
[E-10] Digital Services VAT: How RA 12023 Brought Digital Services Into The Philippine Vat System
[E-11] Create More: Why RA 12066 Rewrote Parts Of The Create Framework
[E-12] CMEPA: How Ra 12214 Changed The Taxation Of Capital Markets And Financial Transactions
[E-13] The Current NIRC: How To Read The National Internal Revenue Code As Amended In 2026
[E-14] How A Philippine Tax Rule Is Born: From Legislation To Implementation
[E-15] How To Research Philippine Tax Law: Finding The Original Rule, Its Amendments, And The Current Legal Basis
Next:
[E-09]
EOPT: WHY RA 11976 CHANGED HOW TAXPAYERS COMPLY
The next major reform moves us away from primarily “How much tax should the taxpayer pay?”
and toward another fundamental question:
“How should taxpayers document, invoice, file, pay, claim refunds, maintain records and deal with the BIR?”
That brings us to the Ease of Paying Taxes Act — RA 11976.
Taxpayer Literacy is a Must!
Editorial Note
Current as of October 31, 2026.
This article is part of the Tax Code Evolution Series of easantoscpa.com Articles & Insights.
The purpose of this series is to help taxpayers understand where Philippine tax rules came from, how they evolved, and why today’s tax rules must be read together with their amendments, implementing issuances and jurisprudence.
Taxpayer Literacy is a Must!
Need Help With a Tax or Compliance Concern?
Understanding your obligations is the first step. Building the right compliance system is the next.
If your business needs professional guidance regarding BIR compliance, bookkeeping, documentation, tax concerns, or compliance review, you may discuss your specific circumstances with us.
BOOK A CONSULTATION →
Disclaimer
This article is provided for educational and conceptual purposes only and does not constitute tax, legal, accounting, or other professional advice. Tax rules and administrative requirements may change, and their application depends on the taxpayer’s particular facts and circumstances. Consult a qualified professional regarding your specific situation.
LEARN • STRENGTHEN • COMPLY
Trainings, Seminars & Webinars
Practical learning for business owners, professionals and teams.
- services@easantoscpa.com
- +63 916 587 1528
- Topaz Building, Kamias Road, Quezon City
- Office visit: By Appointment only.
- Strictly NO Walk-In
- Affiliate: ptabcpsolutions.com
Disclaimer: Posts are provided for educational and conceptual purposes only. They do not constitute professional advice. You are advised to consult a qualified professional regarding your specific circumstances.